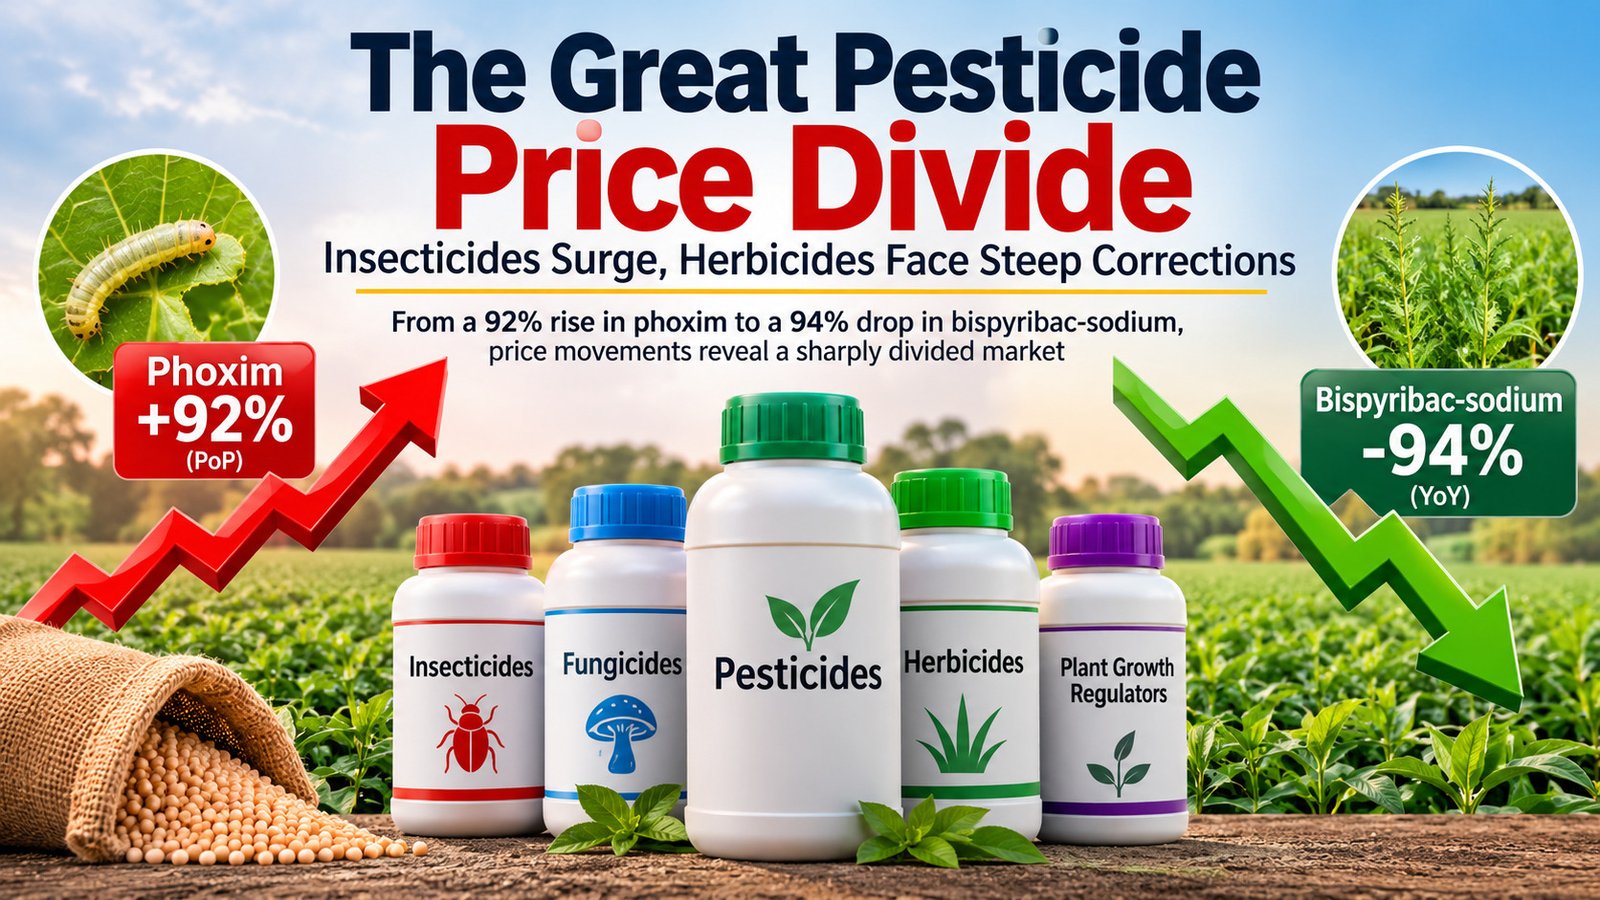
An assessment of 35 pesticide formulations reveals sharp divergences across fungicides, insecticides, herbicides and plant growth regulators. While phoxim prices surged 92 per cent over the preceding period and indole-3-butyric acid climbed 67 per cent year on year, bispyribac-sodium plunged 94 per cent, exposing the increasingly fragmented pricing dynamics of the crop protection industry.
A market moving in different directions
The pesticide market is displaying an increasingly uneven pricing pattern. While several formulations have recorded substantial price increases, others have undergone steep corrections, suggesting that pricing pressures are becoming increasingly product-specific rather than reflecting a broad-based movement across the crop protection industry.
An assessment of 35 pesticide formulations across fungicides, insecticides, herbicides and plant growth regulators, with prices dated October 28, 2026, reveals a market characterised by considerable differences between short-term price movements and year-on-year trends.
The most striking movement is in insecticides, where phoxim 1.5 per cent GR recorded a 92 per cent period-on-period price increase and a 44 per cent year-on-year rise. In contrast, flonicamid 10 per cent WG declined 44 per cent over the preceding period, despite registering an 11 per cent annual increase.
Herbicides present an equally revealing picture. Bispyribac-sodium 10 per cent SC recorded a 94 per cent year-on-year price decline, while cyhalofop-butyl 20 per cent OD registered a 54 per cent period-on-period increase and a 37 per cent annual increase.
The divergence raises an important question for agricultural input manufacturers and distributors: are these movements indicative of broader changes in input economics, or are they primarily reflecting individual product-market dynamics?
The available price data do not establish a common cause. However, they demonstrate that pesticide pricing can no longer be assessed through category-wide averages alone.
Insecticides: The sharpest short-term volatility
Insecticides account for 12 of the 35 formulations in the assessment and display some of the most pronounced price movements.
Phoxim 1.5 per cent GR stands out with a 92 per cent period-on-period increase, taking its listed price to RMB 5.75. Its year-on-year increase of 44 per cent reinforces the scale of the upward movement.
Thiamethoxam 0.08 per cent GR also recorded increases of 33 per cent across both comparison periods, with its listed price reaching RMB 20. Azadirachtin 1 per cent ME rose 40 per cent period on period, although it remained 14 per cent below its year-earlier price.
The picture changes considerably across other formulations. Flonicamid 10 per cent WG declined 44 per cent period on period, while insecticidal powder 0.6 per cent DP fell 25 per cent across both comparison periods. Clothianidin 0.06 per cent GR registered a relatively modest 3 per cent period-on-period decline but remained 22 per cent lower year on year.
Matrine formulations also moved in different directions. Matrine 0.5 per cent SL recorded a 7 per cent period-on-period increase but remained 27 per cent below its year-earlier level. The 1 per cent SL formulation declined 8 per cent across both periods.
This divergence suggests that insecticide pricing is being shaped by individual formulation dynamics rather than a uniform upward or downward movement across the category.
Fungicides: Annual increases coexist with short-term corrections
The fungicide segment presents a relatively stronger year-on-year picture, although its short-term movements remain mixed.
Seven of the nine listed formulations recorded positive year-on-year price changes. Hexaconazole 10 per cent SC registered a 50 per cent annual increase, while oligosaccharins 0.5 per cent AS also rose 50 per cent despite a 40 per cent period-on-period decline.
Prochloraz 15 per cent ME recorded a 33 per cent annual increase, while polyoxin 10 per cent WP rose 13 per cent across both comparison periods.
Physcion 0.1 per cent AS registered a 40 per cent period-on-period increase, although its annual increase was a more moderate 8 per cent. Beta-sitosterol 0.06 per cent ME rose 25 per cent over the preceding period and 11 per cent year on year.
However, the declines are equally significant. Eugenol 0.3 per cent SL fell 27 per cent period on period and 38 per cent year on year. The listed price of abamectin plus fosthiazate 10 per cent GR declined 29 per cent over the preceding period and 20 per cent annually.
The overall pattern indicates that the fungicide segment has retained a positive annual pricing bias across most of the sampled formulations, but that does not translate into consistent upward movement in the immediate pricing cycle.
Herbicides: The steepest annual price correction
If insecticides demonstrate the sharpest short-term volatility, herbicides reveal the most pronounced annual price corrections. Bispyribac-sodium 10 per cent SC recorded the steepest decline in the entire assessment, falling 94 per cent year on year to a listed price of RMB 4.50. It also registered a 25 per cent period-on-period decline. Diquat 10 per cent AS fell 37 per cent year on year, while fluoro...glycofen-ethyl 10 per cent EC declined 33 per cent. MCPA plus pyrazosulfuron-ethyl 18 per cent WP registered a 40 per cent decrease across both comparison periods.
These movements contrast sharply with the performance of other herbicide formulations. Cyhalofop-butyl 20 per cent OD rose 54 per cent period on period and 37 per cent year on year, reaching RMB 18.50. MCPA-sodium 11.7 per cent AS increased 32 per cent annually, while the combination of 2,4-D and glufosinate-P 12 per cent SL recorded a 10 per cent increase across both periods.
Glufosinate-P-ammonium 10 per cent SL, meanwhile, declined 21 per cent over the preceding period but remained 10 per cent higher year on year. The contrast suggests that herbicide pricing is particularly sensitive to formulation-specific market conditions. The steep decline in bispyribac-sodium, alongside the sharp increase in cyhalofop-butyl, illustrates why treating herbicides as a single pricing category can conceal substantial differences in market behaviour.
Products experiencing sustained price erosion may face greater pressure on commercial realisation, while formulations recording significant increases may offer stronger pricing opportunities, subject to demand and competitive intensity.
Plant growth regulators: A small segment with substantial price swings
Plant growth regulators account for six products in the assessment, but their price movements are among the most pronounced.
Indole-3-butyric acid 1 per cent SL recorded a 48 per cent period-on-period increase and a 67 per cent year-on-year rise, taking its listed price to RMB 5. Gibberellic acid 20 per cent SP also registered substantial increases of 45 per cent and 60 per cent, respectively. The 24-epibrassinolide 0.01 per cent SL formulation rose 43 per cent period on period and 25 per cent annually.
However, other formulations experienced considerable corrections. Brassinolide 0.004 per cent AS declined 33 per cent over the preceding period and 25 per cent year on year. The 1-naphthylacetic acid 20 per cent DP formulation fell 27 per cent and 20 per cent across the respective comparison periods. The 2,4-D sodium salt 2 per cent AS formulation also declined 21 per cent period on period and 8 per cent annually.
The data suggest that the PGR segment is not following a common pricing trajectory. While selected formulations are registering substantial increases, others continue to experience price corrections. What the numbers mean for the crop protection industry
The most important takeaway from the assessment is not that pesticide prices are rising or falling. It is that the market is becoming increasingly differentiated at the formulation level.
Of the 35 products assessed, 18 recorded period-on-period price increases, while 17 registered declines. The year-on-year comparison was equally revealing, with 20 products recording price increases and 15 registering declines.
Three developments deserve particular attention.
First, pricing power is unevenly distributed. The 92 per cent increase in phoxim, 54 per cent rise in cyhalofop-butyl and 48 per cent increase in indole-3-butyric acid indicate substantial upward movements in selected formulations. However, the declines in flonicamid, bispyribac-sodium and eugenol demonstrate that such increases are far from universal.
Second, short-term price movements do not necessarily reflect the annual trend. Oligosaccharins, for instance, declined 40 per cent period on period but remained 50 per cent higher year on year. Azadirachtin increased 40 per cent in the immediate comparison while remaining 14 per cent below its year-earlier price. Such differences matter when manufacturers and distributors assess inventory costs and procurement timing.
Third, price corrections can be as consequential as increases. The 94 per cent annual decline in bispyribac-sodium is particularly significant and warrants closer examination of its underlying market conditions. However, without production, sales-volume, inventory and raw-material data, it would be premature to attribute the decline to oversupply, demand weakness or competitive discounting.
Input economics: The missing link in pesticide pricing
For the agricultural inputs industry, the next question is whether these finished-product price movements are translating into changes in manufacturing margins. A pesticide's market price is influenced by several variables: technical-grade active ingredient costs, formulation expenses, packaging, logistics, regulatory compliance, distribution margins and competitive positioning.
A decline in the price of a finished formulation does not automatically mean that its manufacturing cost has fallen. Equally, an increase in the selling price does not necessarily translate into improved profitability if raw-material and operating costs have risen simultaneously. This distinction is particularly important for formulation-led businesses, which may face different margin pressures depending on their sourcing arrangements, manufacturing efficiencies and exposure to imported technical materials.
For distributors, price volatility can create additional inventory risks. Stock purchased at higher prices may become commercially difficult to liquidate if market quotations decline sharply. Conversely, rapid price increases can raise replacement costs and complicate procurement decisions.
Farmers ultimately face a different calculation: the cost of crop protection relative to the value of the crop being protected. Even when individual pesticide prices decline, the overall cost of cultivation may remain under pressure because of higher application requirements, labour expenses, fertiliser costs or the need for additional pest and weed management interventions.
From price movements to market strategy
The pesticide market's latest price movements point to a more complex commercial environment for manufacturers, distributors and farmers. For manufacturers, portfolio-level pricing strategies will need to account for the varying trajectories of individual formulations rather than rely on broad assumptions about category inflation. For distributors, inventory discipline and procurement timing become increasingly important when short-term and annual price movements diverge. For farmers, the relevant metric remains the total cost and effectiveness of crop protection rather than the price of an individual formulation in isolation.
The October 28 price snapshot does not establish whether the market is entering a sustained inflationary or deflationary phase. What it does establish is that price discovery across pesticide formulations is far from uniform. The next phase of market analysis must therefore look beyond listed prices to technical-grade costs, production volumes, inventory positions, demand across major crop cycles and the competitive dynamics of individual active ingredients.
For the crop protection industry, the challenge is no longer simply to track whether prices are moving up or down. It is to understand which products retain pricing power, which are losing ground, and whether either movement is translating into healthier margins across the value chain.
Source: CCM-cnchemicals